Cyber Security for High Net Worth Individuals and Executives
Cyber security for high net worth individuals, executives and family offices. Protect personal accounts, verify payment changes and reduce family exposure.
A household review identifies who controls personal accounts and who can help restore access.
Start with a Private Household Cyber Review
Map how personal phones and email accounts are recovered, and who can step in if a device or number is lost. Agree with your family office and bank how staff should verify new wire instructions.
Give family members and assistants a short playbook for unusual requests. With a parent or guardian, review children’s account settings and public exposure. The Dossier records the priority findings, who can act and how to check the outcome.
Exposure around a principal
An adviser, assistant, supplier, or family member can receive a convincing request that appears to come from someone they know. Public professional details can make those requests easier to believe.
Household networks and travel
Discuss whether work, household devices, and visitors should use separate networks. Before travel, decide which devices or accounts are necessary and who to contact if access is interrupted.
A written household policy
Write down how people should verify changes to payment details, new access requests, and unusual instructions. Keep the process clear enough for family, staff, and advisers to use.
Coordinate with a trusted advisor and personal staff
Agree who may commission or receive a review and who handles technical changes, removal requests, and communications. Share each finding only with the people designated to act on it.
Ways to begin
Start with a single Dossier or discuss a broader scope across households or offices. Agree on what needs follow-up before adding ongoing checks.
What should household staff do with a last-minute payment request?
Give the person who pays invoices a number they can call when an instruction changes. A driver, assistant or house manager should be able to pause a payment without first proving a message is fraudulent. Practice with a routine supplier invoice before a real deadline.
Where personal and executive risk meet
A chief executive may have a company-managed laptop and a personal email account that receives school, banking and travel notices. Corporate security can protect the first without seeing the second.
Start by identifying which personal accounts can reset others, who holds recovery access and where the executive wants an assistant involved. Keep the boundary explicit when asking an employer for help.
How to evaluate elite cyber security for high net worth individuals
Ask a provider to walk through a specific decision.
If an assistant receives an urgent request from the principal’s personal address, who verifies it, who can pause a transfer and who tells the family office? Ask for a sample finding that identifies the source, the person responsible and a way to check the outcome. For private clients, a credible risk management plan names who can make a security decision and how the family office can verify it.
After a public appointment or transaction
Before a board announcement, decide which biography, photograph and professional contact details may be published. Check whether the published material leads directly to a residential address or a family member’s personal profile.
Assign corporate changes to the communications team and household decisions to the principal. Review both sets after the announcement goes live.
Which cybersecurity threats should high net worth individuals address first?
Rank findings by what they would allow someone to do. A public interview might identify the family office; a supplier directory might reveal who handles transfers.
Together, those details can make a phishing email sound routine. Give the people who approve financial transactions a way to verify changes independently. Keep sensitive family information out of the approval record unless the decision requires it.
Protect family members from identity theft and account loss
Consider a lost phone on the morning of a flight. If the device holds the only recovery method for personal email, the loss can affect banking, travel and household communications at once.
Identify an alternate recovery route the principal controls. Give family members a known contact for urgent requests, then test the arrangement without sharing passwords or verification codes.
When social media exposure becomes a physical security concern
A public photograph can disclose more than a name. A school uniform, driveway or view from a hotel window may reveal where family members spend time.
Check the original post, the audience and who can change it. If a post includes a credible threat, involve the person responsible for physical security promptly. Keep the underlying family details within the group authorized to handle them.
A practical first review for financial accounts
List the accounts used to authorize transfers, recover email and approve a new payee. Note who controls each recovery address and how a second person verifies an unusual instruction.
An adviser can help confirm the bank’s process without collecting the client’s passwords. Test one ordinary scenario: an assistant receives new payment details for a familiar vendor while the principal is flying. Everyone should know who can wait, who can verify and who can release the payment.
High net worth cyber security starts with the accounts that unlock the rest
For high net worth individuals, a personal mailbox can be the recovery address for financial accounts, cloud storage and social media accounts. Even a strong corporate cyber security program may have no authority over it. Personal cyber security gives the principal a way to secure these accounts separately.
Our review traces those dependencies with the executive and the family office. Start with the account that could do the most damage if someone else controlled it. Check its signed-in devices, recovery contacts and multifactor authentication. Then agree who can help restore access if the principal loses a phone abroad.
Identity theft and the family’s public record
An executive’s biography may identify a spouse. A charity photograph can connect that name to a school. Data brokers may connect both to an address. Together those details can make an impersonation attempt credible or introduce physical security risks.
Review public records and social media exposure with the affected family members. This is especially important for wealthy families whose personal details are already exposed online through previous public appearances. In the Dossier, distinguish a listing that can be removed from an official record that remains public. Recheck the source after a removal request and record what a stranger can still see.
How family offices verify financial transactions
An assistant receives a voice message asking for a deposit before the principal boards a flight. Artificial intelligence can imitate a familiar voice. The safest decision is the one agreed before the deadline.
For changes to wire instructions, call the beneficiary on an independently recorded number and have a second authorized person approve the transfer. Family offices can agree transaction limits and account alerts with the bank. If money has already moved, call the bank’s fraud team immediately using a trusted number. Keep the original instructions for its investigation.
Before approving a change in wire instructions, call the supplier on a number the family office already trusts.
Phishing scams and social engineering targeting family members
A school invitation, a parcel notice or a request from an executive assistant can lead to the same fake sign-in screen. Cybercriminals target daily activities because routine requests attract less scrutiny. Give family members permission to pause a request, including one that appears to come from the principal.
Use the institution’s saved app or website to check it. If someone has already entered credentials, contact the account provider from a trusted device, change the password and review active sessions and recovery methods. Tell the family office if the account could have been used to request money or sensitive information.
Dark web monitoring and threat intelligence for private clients
A dark web monitoring alert may show that an old email address appeared in a breach. It cannot establish by itself that a current financial account was compromised.
Useful threat intelligence connects the alert to a decision. Was the exposed password reused? Can that mailbox reset another service? Who will confirm the change? For high net worth individuals with overlapping business and private interests, record which findings belong with corporate information security, private security or the family office. Keep sensitive data out of routine status updates.
Travel security for executives and their personal devices
Before a trip, review the threats around the travel destination, the personal devices the traveler needs and the most sensitive cloud accounts. Prepare a secure way to reach critical services if a device is lost. Remove unnecessary local copies of sensitive documents and agree secure communication channels with the assistant at home.
Check how to reach the mobile carrier if a phone is lost. A virtual private network can protect traffic on an untrusted network, but it cannot establish that a payment instruction is genuine. Give travel staff a separate itinerary with only the details they need.
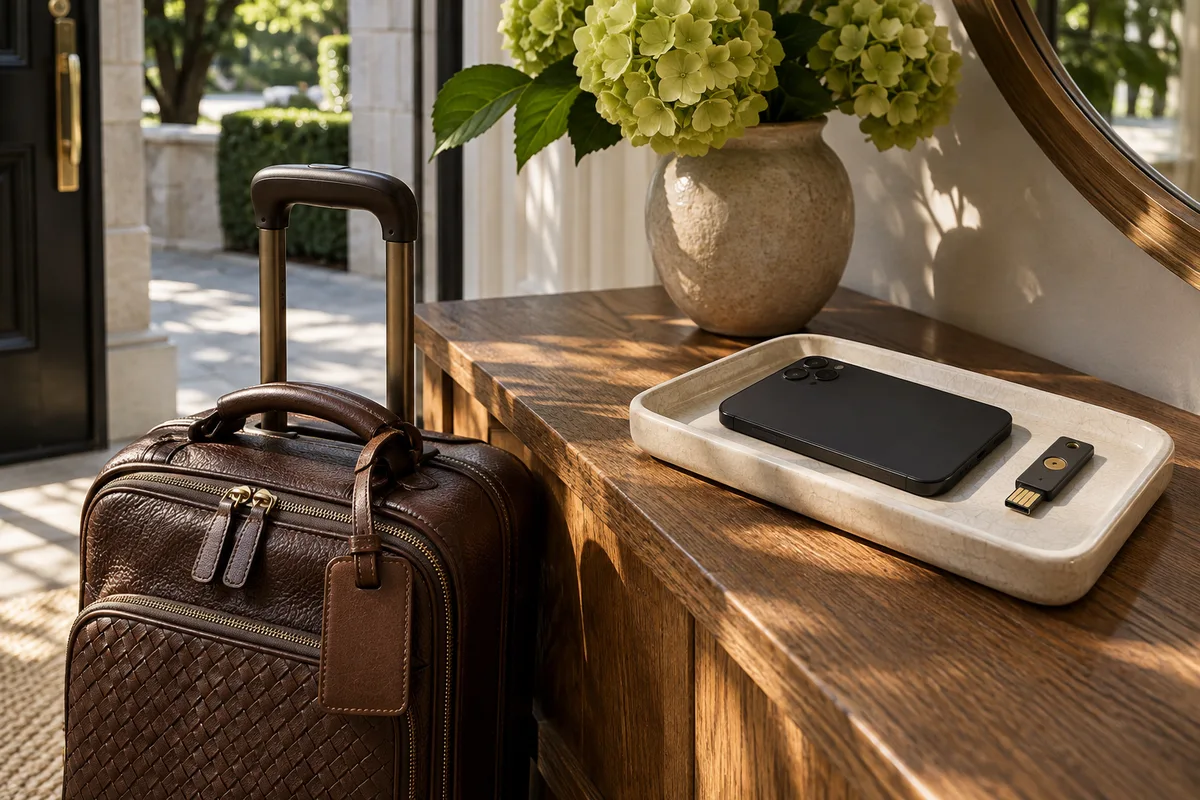
Test account recovery before travelling so losing one phone does not lock you out of email and banking.
What should a family office receive after a risk assessment?
Ask for a short decision list the principal can use. Which cyber threats need attention first? Which family members or advisers have authority to act? What evidence will close each finding? Keep the original source and review date alongside the action.
A second review can distinguish changes in the family’s security posture from old findings that reappeared. Ask which preventive controls protect the family’s assets, what could still produce potential losses and who accepts the remaining risk. Schedule risk assessments around events that change exposure, such as a new residence, a public appointment or a change of assistant.
When cybersecurity threats become physical threats
A public photograph of a child at a familiar entrance can reveal more than the caption. Before a family trip or public event, have family members review social media accounts for live locations, identifiable routines and posts shared by others.
Agree which details the family office may pass to private security. If a threat identifies a current address or an imminent visit, preserve the message and involve the people responsible for immediate safety. Deleting a post alone does not resolve physical threats.
Who takes the first call after a security breach?
Decide in advance who coordinates incident response outside the company. The same first contacts are useful after several types of cyber attacks, from financial fraud to a compromised personal account. If targeted cyber attacks involve an executive’s personal phone, the family office may need the carrier to restore control, the bank to review financial accounts and corporate information security to check work access.
Use a separate trusted device for those calls. Give each team the minimum sensitive information it needs. Ask for a reference number and record the time so the next person can follow up without repeating the entire account.
What does personal cybersecurity cover outside corporate IT?
Personal cybersecurity services can cover personal email, mobile carrier accounts, family devices, home networks and the public digital footprint around a principal. The Private Household Cyber Review starts with the services a household relies on and the people who run them. The family office may authorize the work.
A member of staff may administer the gate or approve supplier payments. A corporate security team may manage a work laptop that uses household Wi-Fi. Document the owner and the person who can change each control, then arrange a handover between those teams where their responsibilities meet.
Protect sensitive data with stronger account recovery
Use distinct, strong passwords and multi-factor authentication for accounts that hold sensitive information. Where supported, use a passkey or suitable hardware security key for phishing-resistant authentication. Protect the mobile carrier account with a PIN and the strongest account controls it offers.
Record a second approved recovery method and test it before travelling. A principal may hold a backup security key in a secure location and give an adviser the provider’s contact details rather than the keys themselves. Check that an old assistant or a former business address has been removed from the account recovery settings.
Household network security and connected devices
Ask the installer which accounts can administer cameras, locks and home automation, who receives security updates and which devices need remote access. Put guests and connected devices on appropriate separate networks where the equipment supports it.
Before removing access, confirm that the household has a working way to use critical devices locally. In a multi-property review, record each location separately so that a successful access change at one home does not obscure an unresolved risk at another.
How can family offices reduce financial fraud?
Agree how staff approve new payees, verify supplier changes, and reach the bank if a transfer has already been sent. Separate the ability to enter new instructions from final approval where the bank and office systems support it.
Keep a record of the contact number and approval path when a supplier starts work. This is especially useful during a renovation, property purchase or family trip, when many payments and legitimate last-minute changes arrive at once.
Digital footprint and reputation for high net worth families
Public figures and wealthy individuals may have a digital presence across corporate biographies, charities, boards and social media. Wealthy families can review which details need to be public and which only help an outsider piece together personal relationships or travel patterns. Look at an actual biography or event page with the people who maintain it.
A family member may be able to edit a social profile. A company communications team may control the biography. Prioritize the sources that connect a name to a current home, upcoming public appearances or a person authorized to act on the family’s behalf.
Check who can restore access before something goes wrong
Proactive protection includes rehearsing recovery. Pick one ordinary scenario, such as a principal replacing a lost phone.
Confirm which device receives security alerts, who has the carrier’s support information and how to reach the bank without using the missing device. Keep these instructions available to a trusted person without giving them access to sensitive data. For high net worth families with homes or travel destinations in more than one country, check whether support numbers and approved recovery methods work when someone is abroad.
Create a departure checklist for household staff
When an assistant, contractor or house manager leaves, list the access that person had to residences, shared calendars, document folders and supplier accounts. Assign each removal to the administrator who can perform it.
Revoke individual access and test any shared service the household still needs. Move useful institutional knowledge, such as a trusted contact number or a service renewal date, into records the household controls. Set a reminder to revisit any change that requires the bank, installer or another security provider.
Can you coordinate with our existing security team?
Yes. Agree which people and systems fall within each team’s remit at the start. A family office may coordinate financial controls, an estate manager may own household technology, and a corporate security team may support work devices.
Share a summary of each agreed action and who verifies it. For sensitive findings, share only the details each recipient needs. This gives the principal a record of what changed across their digital life and which risks should be revisited after a move, staffing change or cybersecurity incident.
How threat intelligence supports wealth management
A useful threat intelligence review asks what information would let someone impersonate a principal, disrupt a planned transaction or cause reputational damage. Wealth management advisers can help confirm who handles unusual requests, which financial accounts need independent verification and how the bank contacts the family.
Ask which signals the service will review and which are out of scope. Threat intelligence can inform threat detection when a trusted provider reports data breaches, misuse of a contact address or a new impersonation attempt. Agree how to assess emerging threats against the client’s actual exposure before asking anyone to act.
Recovery after ransomware attacks or loss of a device
Before an incident, identify which personal documents need a backup and who can restore them. Test recovery on one file. Ask whether the backup service can restore an earlier version and what happens if the same account that controls the device is compromised. A recovery test can uncover gaps before assets are lost or threats escalate.
If a device is suspected of being compromised, contact a trusted support provider from another device. Decide what records to preserve and which accounts the household needs to secure first. Separate the risks to online accounts from the risk to files on the device. Tell family members who is handling each decision and when they can expect an update.
Which risks should a family review again?
Review cyber threats again after a move, major transaction, leadership appointment or a change of staff. A short review can identify vulnerabilities left by an old vendor, changes in who can recover an account and new public information that can help cybercriminals target the household.
To help prevent cyber attacks, prioritize work people can maintain. Give the family office a schedule for checking access to sensitive data, confirming which backup works and rehearsing who verifies payments. The exercise connects cybersecurity protection to practical risks around money, reputation and the safety of family members.
A shared scope
Agree which people, households and staff are in scope. Separate the information each person needs from findings that should be shared only with the principal or a designated adviser.
Follow-up across households
Record what was found, who owns each action, and when it should be revisited. We discuss device or network work separately when it falls outside the initial review.
Can advisers participate?
Yes, when agreed with the principal. We can define which findings the adviser needs and who should receive the full report.
A message about a transfer can use real names, travel plans and the voice of a trusted adviser. Agree in advance who can authorize a change of instructions and how the office confirms it through an established contact. Bring the people who carry out that check into the family office review. For a review centered on the properties themselves, see luxury cybersecurity services.